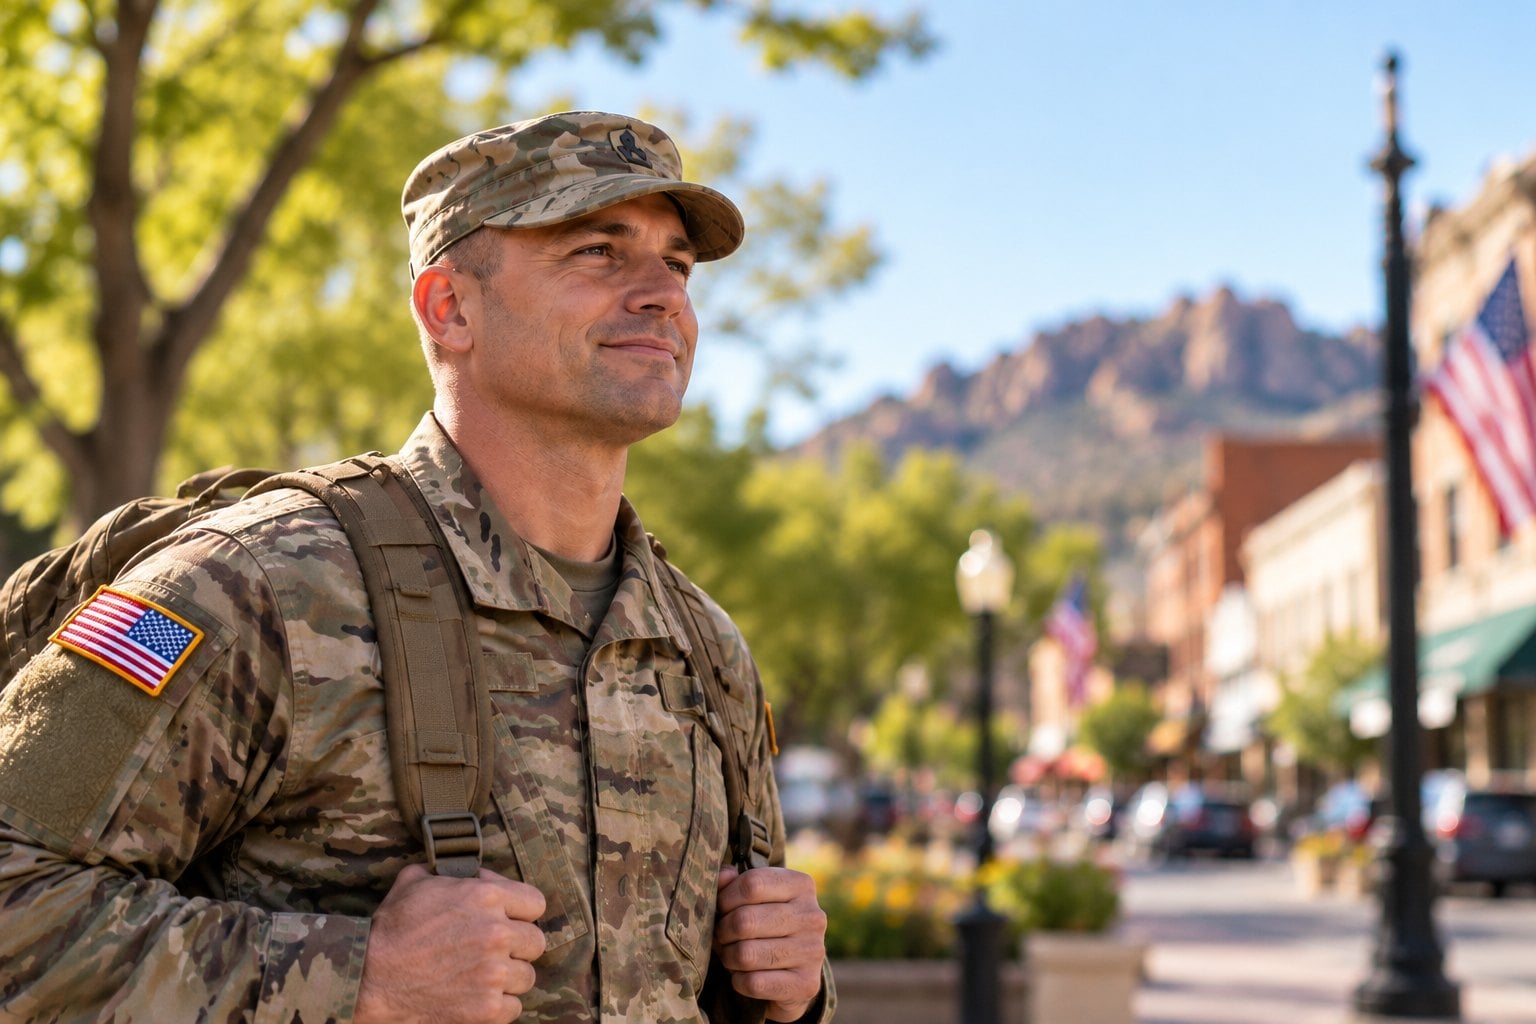
You served. Now you’re ready to put down roots, and Greater Prescott is one of the most popular places in Arizona for veterans to do it. Four seasons, a strong veteran community and a VA Medical Center right in town make it an easy choice. The VA home loan you earned is one of the most powerful tools you’ll ever have for buying a home here. Here’s how it works, what’s changed recently and how to use it to win the right home.
Why Veterans Choose Prescott
Prescott has long been a hub for military families and retirees. The Bob Stump VA Medical Center, part of the Northern Arizona VA Health Care System, sits on the historic Fort Whipple campus, so care is close by. Add mild summers, trails and lakes, and a small-town feel within two hours of Phoenix, and it’s easy to see why so many veterans make Prescott, Prescott Valley and Chino Valley home.
What Makes a VA Loan Different
A VA loan is a mortgage from a VA-experienced lender that’s partially guaranteed by the U.S. Department of Veterans Affairs. That guarantee is what unlocks benefits most buyers can’t get:
- No down payment required. Eligible buyers can finance up to 100% of the purchase price.
- No monthly mortgage insurance. Unlike most low-down-payment loans, VA loans don’t carry PMI.
- Competitive rates. VA loans often come with lower interest rates than conventional loans.
- No loan limit with full entitlement. If you have your full entitlement, the VA doesn’t cap how much you can borrow. Your income and the lender’s approval set your budget.
- Limits on closing costs. The VA restricts certain fees veterans can be charged, and sellers can contribute toward your costs.
Who Qualifies
Eligibility depends on when and how long you served. In general, these groups can qualify:
- Active-duty service members after meeting minimum service time
- Veterans who met the service requirements for their era and weren’t dishonorably discharged
- National Guard and Reserve members with enough qualifying service
- Certain surviving spouses of service members who died in service or from a service-connected disability
Your first step is a Certificate of Eligibility (COE). A VA-experienced lender can usually pull it for you in minutes.
The VA Funding Fee
Most VA buyers pay a one-time funding fee, which can be rolled into the loan. For a first-time VA purchase with no down payment, it’s 2.15% of the loan amount, and it drops if you put 5% or more down. It’s higher if you’ve used your benefit before. Many veterans pay nothing at all: if you receive VA compensation for a service-connected disability, you’re generally exempt.
What’s Changed Recently
After the 2024 changes to how real estate commissions work, the VA updated its rules so veterans can pay their own buyer’s agent when a seller won’t. The VA has since made that policy permanent. In practice, that means you can hire your own agent to represent you, just like any other buyer, and negotiate with the seller to cover that cost as part of your offer.
Extra Help for Arizona Veterans
Arizona offers a property tax exemption on a primary residence for qualifying disabled veterans, and 2026 legislation expanded it, including a full exemption for veterans rated 100% service-connected disabled. Rules and income limits apply, so check with the Yavapai County Assessor’s office before you count on it. Ask us about first-time buyer and down payment programs too. Some can be combined with a VA loan.
Verify with your lender
VA rules, funding fees and tax programs change. Confirm the details for your situation with your lender, or contact our preferred lender, Josh Shirota, for a free review of your VA benefit.
How to Win With a VA Offer in Prescott
Some sellers still assume VA offers are harder to close. A strong team proves them wrong. Here’s the plan we use with our veteran clients:
- Get fully pre-approved first. A pre-approval from a local, VA-experienced lender tells sellers your financing is solid.
- Plan for the VA appraisal. VA appraisals check that a home is safe and sound. Your agent will flag likely repair items before you write the offer.
- Write a clean, confident offer. We position your terms to compete, including how seller concessions and agent compensation are handled.
- Close on time. Your lender and our full-time transaction team coordinate every deadline from contract to keys.
Our Preferred VA Lender: Josh Shirota
We work closely with Josh Shirota and The Elevated Team at CrossCountry Mortgage. Josh knows the Prescott market, offers fast pre-approvals, and keeps processing and underwriting in-house, so VA files stay on schedule. His clients rate him 4.97 out of 5 from 61 reviews.
Josh Shirota, Senior Loan Officer
The Elevated Team at CrossCountry Mortgage
NMLS #874132 | CrossCountry Mortgage NMLS #3029
928.463.3404 | [email protected]
Get Pre-Approved
You’re never required to use our preferred lender. You’re free to choose any lender you like.
Thank You for Your Service. Let’s Get You Home.
You earned this benefit. The right team makes sure you get the most from it: a strong VA pre-approval, an agent who knows how to write a VA offer that sellers take seriously, and a lender and agent who talk to each other so your closing stays on schedule.
Take the first step today. There’s no cost and no obligation:
- Get pre-approved with Josh Shirota. Josh will review your VA eligibility, confirm your Certificate of Eligibility, and show you what you can comfortably afford, often within a day. Call or text 928.463.3404, email [email protected], or start your pre-approval online.
- Talk with a HYLAND GROUP agent. We’ll walk you through VA-friendly neighborhoods, set up a custom home search, and show you homes before they hit the market. Call 928-445-2100 or contact our team.
The HYLAND GROUP has been the #1 team in the Prescott area since 2012, and we’ve helped more than 4,300 families buy and sell. We’d be honored to help you put your VA benefit to work.
Sources
- VA: Eligibility for VA home loan programs
- VA: Funding fee and closing costs
- VA: Home loan limits
- VA Loan Network: VA buyer-broker fee rule made permanent (2026)
- Arizona Legislature: HB 2120, Laws 2026, Chapter 82
- VA Northern Arizona Health Care: Bob Stump VA Medical Center
This article is for general information only and isn’t financial or legal advice. VA loan eligibility, funding fees and program rules are set by the U.S. Department of Veterans Affairs and can change. Property tax exemptions are administered by the county assessor. All loans are subject to underwriting approval; this is not a commitment to lend. Equal Housing Lender.